Life changes quickly. You might change jobs, start a small business, or miss an enrollment deadline. Suddenly, you find yourself living without health insurance.
If you are between the ages of 28 and 63 and earn more than $35,000 a year, you occupy a unique position in the healthcare market. You earn too much to qualify for state-subsidized care, yet you may have missed the annual window to buy standard, comprehensive health coverage. Paying out-of-pocket for every doctor visit or unexpected emergency creates constant financial worry.
At Matched Benefits, we understand how stressful it feels to navigate healthcare options on your own. You want clear answers, predictable costs, and protection against unexpected medical bills.
Find Your Coverage Match
Fortunately, traditional ACA (Affordable Care Act) plans are not the only road available. A range of non-ACA coverage options exists to help bridge your gap, safeguard your hard-earned savings, and give you peace of mind.
This guide breaks down non-ACA health options in simple, everyday language. You will learn how these plans work, what they cover, where they fall short, and how to choose the right path for your health and budget.
Key Takeaway: You have choices even if you missed Open Enrollment or need flexible, temporary health protection outside standard plans. Exploring non-ACA options allows you to create a personalized safety net that fits your immediate budget.
Section 1: Understanding the Coverage Gap (Why People Turn to Non-ACA Coverage)
Many hardworking adults find themselves without health coverage due to everyday life transitions. Understanding how you arrived at this gap helps you choose the best tool to close it.
Common Reasons for Being Uninsured
- Job Transitions and Career Changes: Leaving a corporate position to launch a business, starting freelance work, or moving between jobs often ends employer-sponsored health benefits.
- Missing Open Enrollment: Standard ACA plans only allow sign-ups during a strict window late in the year. If you miss this deadline and do not qualify for a Special Enrollment Period, you cannot purchase standard comprehensive coverage until the next cycle.
- Rising Monthly Premiums: Full-price major medical plans can prove expensive when you do not qualify for government income subsidies.
- Early Retirement: Adults retiring in their fifties or early sixties often need temporary coverage to protect their assets until Medicare eligibility begins at age 65.
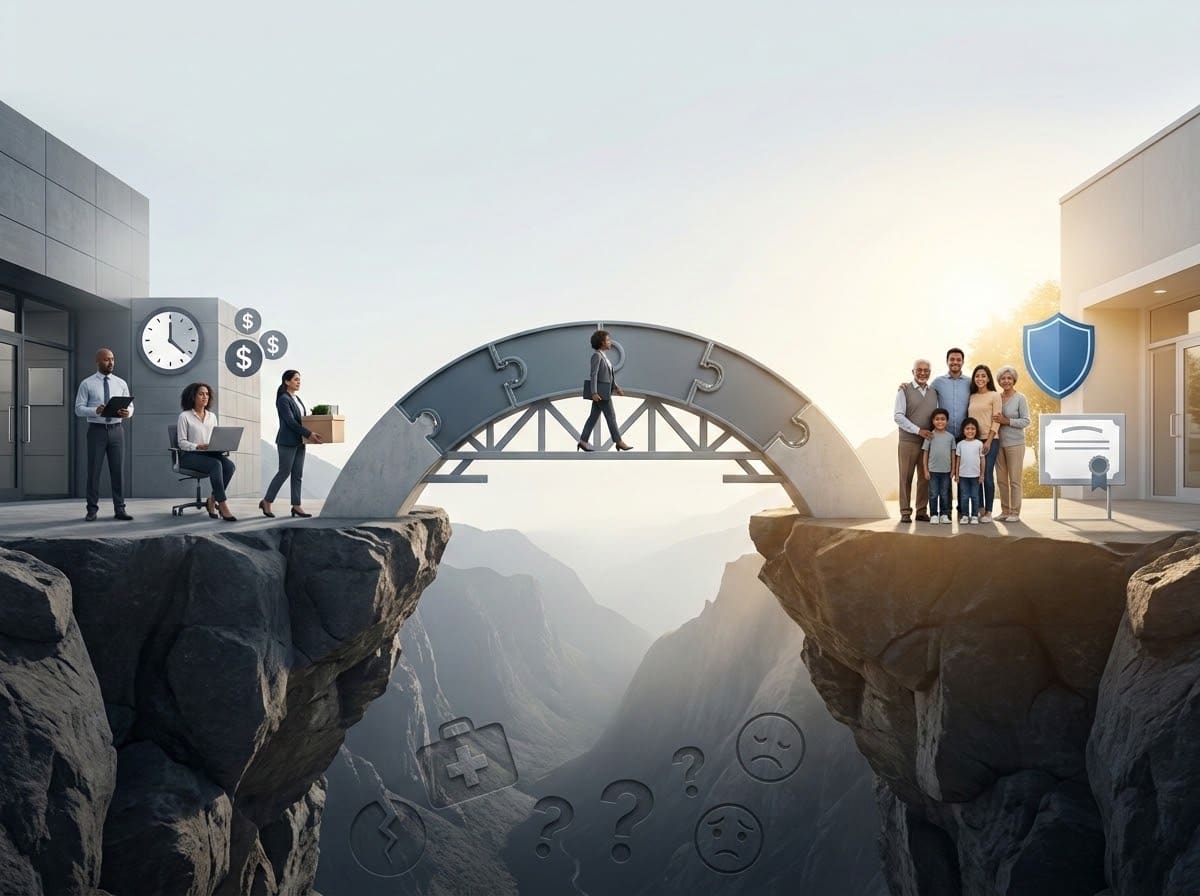
When standard options are out of reach, non-ACA products offer a practical alternative. They provide flexible start dates, custom policy setups, and lower monthly payments. While they do not mirror standard comprehensive insurance, they offer valuable financial protection when used wisely.
Section 2: Deep Dive into Short-Term Health Insurance
Short-term health insurance acts as a temporary safety net. It protects you against major unexpected illness or sudden injury while you wait for long-term coverage to begin.
How Short-Term Plans Work
Short-term plans function similarly to traditional insurance for unexpected medical events. You pay a monthly fee, select a deductible, and the insurer helps pay for covered care after you meet that deductible.
Unlike standard plans, short-term policies have strict duration limits. Depending on state law, coverage can last from 1 month to several months.
Key Benefits of Short-Term Coverage
- Fast Approval: Applications process quickly, and coverage can start as early as the next day.
- Lower Monthly Fees: Monthly premiums are generally significantly lower than non-subsidized ACA plans.
- Catastrophic Protection: They shield your savings from major hospital bills, emergency surgeries, and severe injuries.
Important Considerations: Underwriting and Exclusions
Short-term plans rely on medical underwriting. This means the insurance company evaluates your medical history before approving your application.
- Pre-existing Conditions: These plans almost always exclude existing conditions, such as diabetes, high blood pressure, or prior surgeries.
- Excluded Services: Most short-term plans do not cover routine pregnancy care, mental health services, or prescription drugs for long-term conditions.
Ideal Scenario: Short-term health insurance works best for healthy adults who need temporary protection for a few months while transitioning between major medical plans or jobs.
Section 3: Understanding Fixed Indemnity Plans
If you want predictable cash payouts when medical events occur, fixed indemnity plans offer a straightforward structure.
How Fixed Indemnity Payouts Work
Fixed indemnity plans pay set cash amounts for specific medical services, regardless of what the provider actually charges.
For example, a policy might specify the following fixed payouts:
- $100 for an outpatient doctor visit.
- $500 per day for a hospital stay.
- $250 for an emergency room visit.
- $75 for a diagnostic X-ray.
Cash Benefits vs. Actual Bills
It is vital to understand that a cash benefit pays a fixed rate, not your full medical bill.
Suppose a specialist visits you in the hospital and charges $800. If your indemnity plan pays a fixed $300 for specialist visits, the insurer pays $300. You remain responsible for paying the remaining $500 out of pocket. Conversely, if the bill is lower than the indemnity payout, you keep the difference.
Effective Payout Strategies
You receive fixed indemnity payouts directly unless you instruct the insurer to pay your healthcare provider. This cash flexibility allows you to handle medical bills, replace lost wages during recovery, or cover household expenses like rent and groceries.
Ideal Scenario: Fixed indemnity insurance suits budget-conscious individuals who want guaranteed cash support for specific health events to offset routine care or hospital stays.
Section 4: Exploring Medical Discount Programs
Medical discount programs provide direct cost savings on health services, but they are fundamentally different from insurance products.
Clarifying the Difference: Discount Plans Are Not Insurance
Medical discount programs do not pay medical bills or reimburse you for expenses. Instead, they give you access to a network of medical providers who agree to charge reduced rates to program members.
| Process Step | Description |
|---|---|
| 1. Pay Monthly Fee | Gain access to the participating provider network. |
| 2. Visit Doctor / Provider | Receive care from an in-network medical professional. |
| 3. Pay Reduced Cash Rate | Pay the discounted rate directly to the provider at time of service. |
How Network Discounts Operate
You pay a small monthly membership fee to join the discount network. When you visit participating doctors, dentists, or pharmacies, you present your membership card. The provider applies the agreed discount, and you pay the reduced balance directly at the time of service.
Primary Areas of Savings
- Prescription Drugs: Substantial savings on generic and brand-name medications at participating pharmacies.
- Dental and Vision Care: Discounts on routine cleanings, fillings, eye exams, and glasses.
- Routine Consultations: Reduced rates for general practitioner visits and telehealth consultations.
Benefits and Limitations
Medical discount plans require no medical underwriting and have no waiting periods. Anyone can join regardless of health history. However, you must ensure your local doctors and facilities participate in the program’s network before signing up.
Section 5: Supplemental Coverage & Health Savings Options
Combining smaller, targeted policy options allows you to build a comprehensive safety net without paying full-price health insurance premiums.
Common Types of Supplemental Coverage
- Accident Insurance: Pays lump-sum cash benefits directly to you if you suffer specific injuries from accidents, such as broken bones, dislocations, or severe burns.
- Critical Illness Insurance: Delivers a lump-sum cash payout upon the diagnosis of covered major conditions, such as a heart attack, stroke, or cancer.
- Hospital Gap Plans: Designed specifically to cover out-of-pocket costs, deductibles, and copays during hospital stays.
Building a Personal Health Savings Strategy
Pairing supplemental plans or non-ACA policies with a dedicated personal savings plan strengthens your financial defense.
Setting aside a portion of your monthly income in an accessible, high-yield savings account creates a personal health reserve. You can use these cash reserves to cover routine wellness visits, deductibles, or unexpected charges that fall outside your plan’s coverage limits.
Section 6: Non-ACA vs. ACA Coverage: A Plain-Language Comparison
To make an informed decision, you must understand how non-ACA alternative plans compare to standard ACA major medical plans.
| Feature | Standard ACA Comprehensive Plans | Non-ACA Alternative Plans |
|---|---|---|
| Essential Health Benefits | Mandatory coverage for 10 broad categories (maternity, mental health, prescriptions, etc.). | Covers specific selected benefits; excludes non-listed services. |
| Pre-existing Conditions | Full coverage guaranteed; cannot deny care or charge higher fees. | Usually excludes or limits coverage for prior medical conditions. |
| Enrollment Windows | Restricted to annual Open Enrollment or Special Enrollment Periods. | Available year-round with rapid, flexible start dates. |
| Medical Underwriting | None allowed; acceptance is guaranteed. | Required for most plans; health history affects approval. |
| Monthly Premium Cost | Typically higher unless you qualify for federal subsidies. | Generally lower monthly costs tailored to specific budgets. |
| Best Suited For | Individuals with chronic health conditions or high care needs. | Uninsured adults needing temporary, flexible, or budget-focused options. |
Honest Look at Trade-Offs
Standard ACA plans offer complete, comprehensive coverage. However, if you do not qualify for subsidies or missed the enrollment window, paying full price may exceed your monthly budget.
Non-ACA plans give you flexibility and immediate protection against high costs. In exchange for lower monthly fees, you accept specific limits, such as medical questions during sign-up and capped benefit payouts.
Section 7: Navigating State Rules & Eligibility Criteria
Your location, age, and income directly influence which health coverage options you can purchase.
Why Location Matters
Healthcare regulations vary by state. Some states allow short-term health plans to run for up to 364 days, while other states restrict them to 3 months or prohibit short-term plans entirely. Fixed indemnity plans and medical discount programs also feature state-specific rules and provider networks.
Age Considerations (Ages 28–63)
Adults between 28 and 63 often face unique coverage challenges:
- You are no longer eligible to stay on a parent’s plan (which ends at age 26).
- You are not yet eligible for Medicare (which starts at age 65).
- Career changes and independent contracting work occur frequently during these decades.
Non-ACA options are designed specifically to provide flexible coverage solutions tailored to adults during these key working years.
Income Benchmarks ($35,000+ Annual Earnings)
Earning more than $35,000 per year means you have meaningful financial assets to protect from sudden medical debt. However, it may also mean you receive smaller subsidies on individual health exchanges, making non-ACA options an appealing, cost-effective alternative.
Section 8: Step-by-Step Consumer Checklist: Before You Choose a Plan
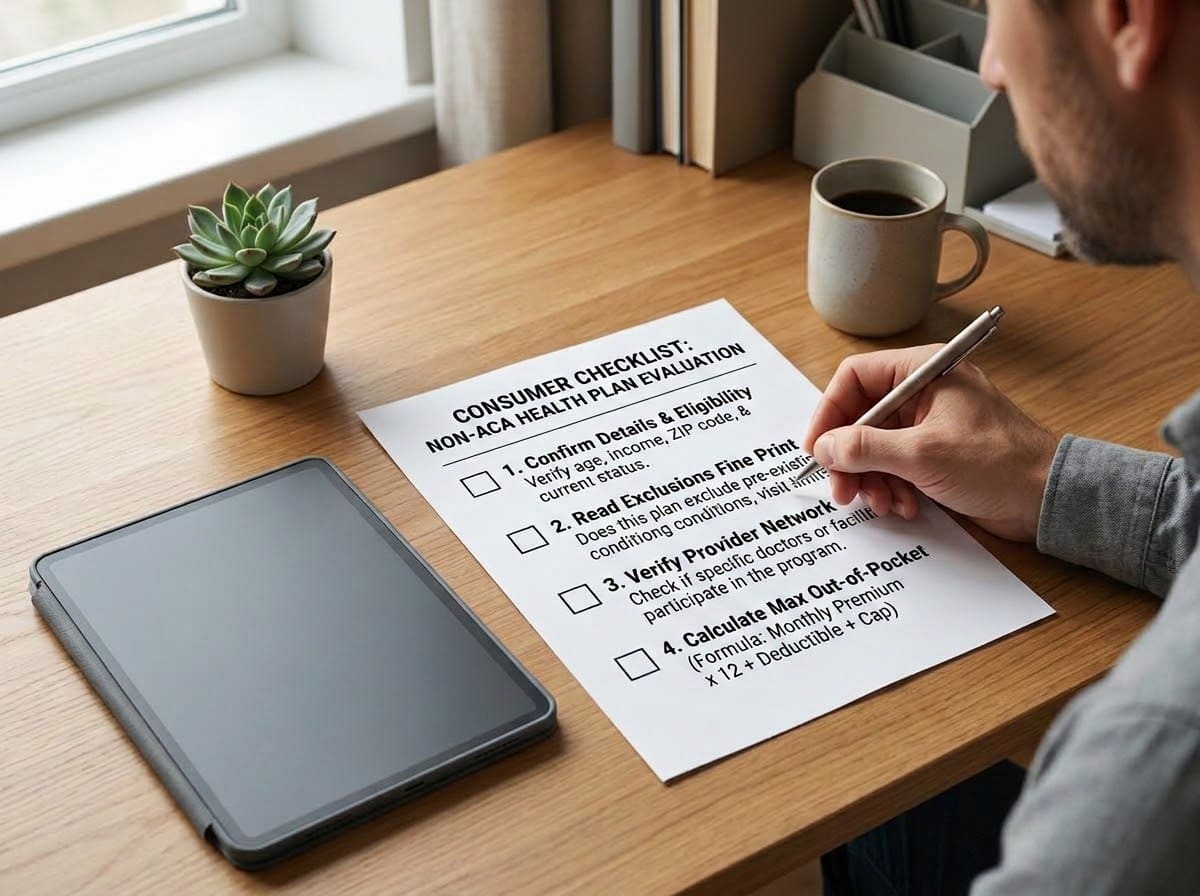
Before purchasing any policy or membership, follow this simple checklist to ensure the plan fits your financial and health requirements.
1. Gather Your Details First
Have these six key pieces of information ready before exploring options:
- Your Exact Age: Confirms plan eligibility for adults aged 28–63.
- Annual Income Estimate: Confirms if your earnings exceed $35,000.
- Current Insurance Status: Confirms you are currently uninsured.
- ZIP Code and State: Determines local plan availability and rules.
- Primary Coverage Goal: Defines whether you need temporary insurance, cash payouts, or care discounts.
- Desired Start Date: Establishes how quickly you need your coverage to begin.
2. Read the Exclusions and Limitations Fine Print
Always read the policy exclusions before signing. Ask yourself:
- Does this plan exclude my pre-existing health conditions?
- Are doctor visits capped at a certain dollar amount or number of visits per year?
- Are prescription medications covered, discounted, or completely excluded?
3. Check Provider Networks
If you prefer seeing specific doctors, verify that they accept the plan’s network or participate in the discount program before you enroll.
4. Calculate Maximum Out-of-Pocket Costs
Do not judge a policy by its monthly price tag alone. Calculate your total exposure:
Total Annual Financial Risk = (Monthly Premium x 12) + Deductible + Maximum Out-of-Pocket Cap
Section 9: Conclusion & Next Steps with Matched Benefits
Navigating healthcare without coverage does not have to feel overwhelming. Being uninsured between the ages of 28 and 63 with an income over $35,000 means you have specific options designed for your situation.
Whether you need temporary short-term insurance to bridge a job transition, a fixed indemnity plan to provide cash payouts for hospital stays, or a discount program to reduce routine prescription costs, non-ACA products offer real flexibility and budget control.
Take Control of Your Coverage Journey
You can make confident healthcare choices when you have clear information.
Visit Matched Benefits online today to explore available non-ACA coverage options, compare plan types, and find resources tailored to your location and budget. Review your needs, prepare your information, and secure the financial protection you deserve.